Monthly Portfolio Review: September 2026

Monthly Portfolio Review: September 2026

September added value to my ISA, but more importantly it changed the shape of my portfolio around the edges while my main concentration stayed intact.

This review covers my IBKR ISA only. It excludes my separate Trading 212 High Growth Challenge, and it is not a recommendation to copy my holdings.

My portfolio snapshot

SnapshotIBKR ISA value
31 August 2026£222,930.28
30 September 2026£248,324.71
Change in displayed account value+£25,394.43 (+11.39%)

This is not a claimed investment return. It is the change in my tracked account value between month-end snapshots, without a full cash-flow attribution. The useful number is the one that helps me keep the record honest, not the one that makes the month look most impressive.

What changed in my portfolio

My core positions remained 2,000 Rocket Lab shares and 250 Palantir shares. Around that core, my month-end records showed Surf Air Mobility at 20,000 shares, Strategy at 100 shares, Rome Resources at 6,000,000 shares and IonQ at 105 shares. Ondas appeared as a new 200-share position in my final snapshot.

Micron, IREN and GoPro did not appear in my 30 September snapshot after appearing at the end of August. That tells me my portfolio changed, but I will not retrospectively invent the rationale for every trade from a holding list alone.

Earlier in the month I wrote that I held some MSTR and BMNR for a little crypto exposure inside my ISA. I treated that as deliberate satellite exposure, not a replacement for the core investment case elsewhere in my portfolio.

What I was watching

  • Whether my core concentration was still doing the job I wanted it to do, rather than just benefiting from a strong tape.
  • Whether my satellite positions had a distinct reason to exist or were simply increasing the number of screens I watched.
  • How much of the month’s progress was changing my behaviour, rather than my underlying conviction.

Where I could be wrong

I still carry meaningful concentration and execution risk. A stronger end-of-month value does not remove financing risk, dilution risk or the possibility that a company thesis takes longer to play out than I expect. My ISA is a proof asset for my process, not a blueprint for someone else’s allocation.

See my live Portfolio, the August 2026 review, and my relevant company writing through the RKLB archive.

Monthly Portfolio Review: August 2026

Monthly Portfolio Review: August 2026

August was a reminder that a concentrated portfolio can make a month look straightforward in retrospect while feeling anything but straightforward in real time.

This is a retrospective record of the IBKR ISA only. It does not include the separate Trading 212 High Growth Challenge, and it is not a model portfolio or a recommendation to copy any holding.

Portfolio snapshot

SnapshotIBKR ISA value
31 July 2026£194,538.84
31 August 2026£222,930.28
Change in displayed account value+£28,391.44 (+14.59%)

That change is not presented as an investment return. It is the change in the tracked account value between the two month-end snapshots, without a full cash-flow attribution. The end-of-month record also matters more than a good-looking moment during the month.

On 25 August, I shared an IBKR screenshot on X showing £229,185.80 and a strong month-to-date move. The validated 31 August snapshot was lower at £222,930.28. That is a small but useful illustration of the point: a concentrated account can move enough in a few sessions to change the emotional story you tell yourself about the month.

What the portfolio looked like

The core stayed concentrated. The 31 August snapshot recorded 2,000 Rocket Lab shares, 250 Palantir shares, 2,001 AbCellera shares and 1,000 BETA Technologies shares. Smaller positions included 18,000 Surf Air Mobility shares, 80 Strategy shares, 1,000 QYLP units and several higher-risk satellite holdings.

I am deliberately not converting every native-currency position into a headline weighting here. The point of a monthly review is to record the shape of the decision, not manufacture more precision than the source data supports.

What I was watching

  • Whether the concentration that created the upside would remain tolerable when the direction reversed.
  • Whether I could distinguish a genuine thesis change from the discomfort of a volatile screen.
  • Whether the portfolio was still serving the wider aim of freedom, rather than becoming a new source of compulsive monitoring.

Where I could be wrong

A small number of growth companies can create a result that looks rational while prices rise and fragile when sentiment changes. Execution risk, financing risk, dilution and valuation compression remain real. The lesson is not that concentration is automatically wrong. It is that concentration asks more of the investor than a good month can reveal.

See the live Portfolio, the previous July 2026 review, and the relevant company writing through the RKLB archive.

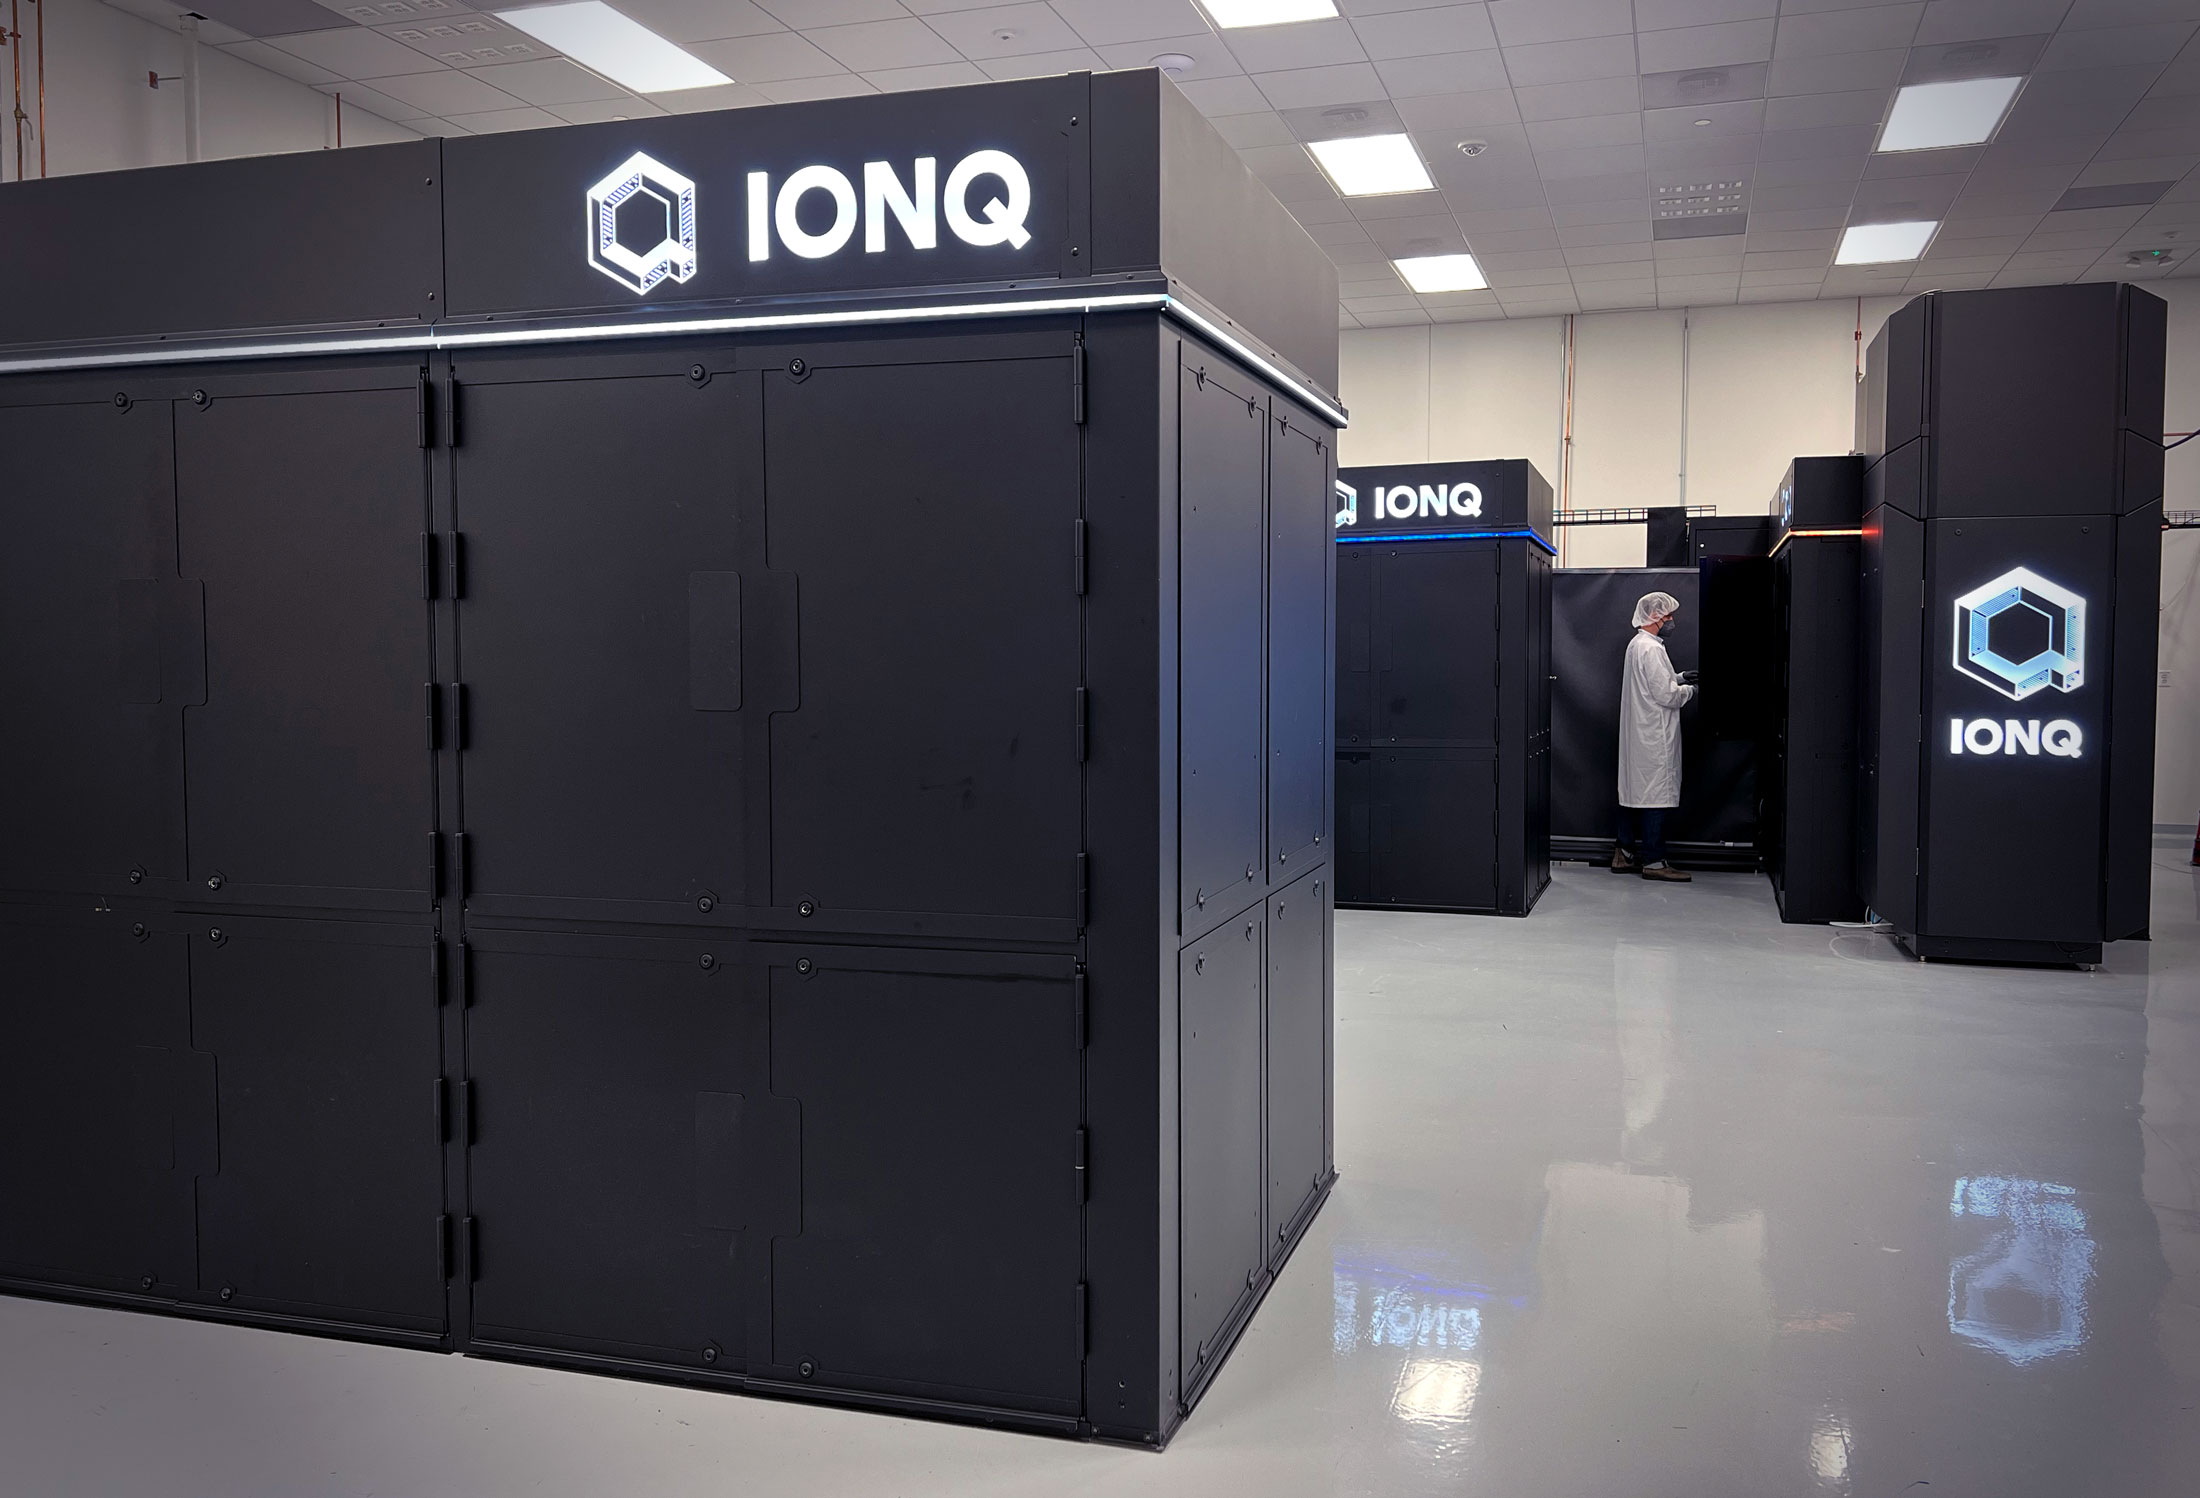
IonQ (IONQ) Investment Thesis: Commercialisation and Revenue Quality

IonQ is one of the more interesting public ways to study whether quantum computing can become a real commercial market. It is also a company where a powerful roadmap can distract from the harder question. For me as a personal investor, the test is not whether quantum will soon transform every industry. It is whether IonQ can turn contracted demand, repeat customer deployments and a widening product set into repeatable revenue with improving economics.

That distinction matters because a quantum company can be technically ambitious, commercially early and expensive all at once. This is a research framework, not a recommendation to buy or sell IONQ.

What IonQ sells today

IonQ sells access to trapped-ion quantum computing systems, including through cloud providers, alongside systems and services aimed at enterprise and public-sector customers. The company is also building adjacent capabilities in quantum networking, sensing and security. Its current commercial proposition is therefore broader than a single future machine. Customers can buy access, deployments and related services while the company continues to develop its hardware roadmap.

The products should still be separated from the narrative around them. Hardware benchmarks and roadmap milestones can help explain why a customer might test a platform, but they are not independent proof of a durable commercial advantage. A useful investor question is whether a system leads to a paid deployment, then a repeat deployment, then a relationship that persists without an unusually large one-off project.

The evidence for commercialisation is improving

IonQ reported $80.1 million of second-quarter 2026 revenue, up 287% year on year. In its official Q2 results release, the company said commercial customers represented about 60% of quarterly revenue, international revenue about 50%, and multi-product revenue about 25%. Those are useful signs that demand is extending beyond a single customer type or geography.

The same release reported remaining performance obligations, or RPO, up 297% year on year. RPO is a useful leading indicator because it represents contracted work not yet recognised as revenue. It is not revenue, cash, a margin guarantee or proof that every contract will convert on the expected timetable. I would treat it as a queue to interrogate rather than a number to capitalise.

Commercialisation is not a roadmap event. It is the repeated conversion of customer interest into delivered work, cash collection and economics that improve as the business scales.

Revenue quality matters more than the headline growth rate

Rapid reported growth is encouraging, but it is not enough on its own. IonQ has made a series of acquisitions, so investors should separate organic quantum-computing demand from acquired revenue and revenue from newer adjacent businesses. Management described Q2 growth as organic in its release. The stronger evidence will be disclosed revenue mix, repeat deployments, retention, conversion of RPO into recognised revenue and cash, and a clearer explanation of what each acquisition contributes.

The Form 10-Q for the quarter ended 30 June 2026 reports $80.1 million of quarterly revenue and $60.1 million of cost of revenue, excluding depreciation and amortisation. That shows why gross margin deserves its own monitoring line. More revenue is valuable only if the company can deliver it without permanently expanding the cost base faster than gross profit.

There is a second discipline. One large contract can produce a striking quarter, particularly in a young market. The more durable pattern would be customers returning for additional systems, capacity, applications or related networking and security work. A healthy backlog should progressively become recognised revenue and operating cash flow, not just a longer list of announcements.

The manufacturing and vertical-integration proposition

IonQ completed its acquisition of Oxford Ionics in September 2025. According to the official completion announcement, Oxford Ionics adds patented trapped-ion technology manufactured using standard semiconductor chips. That could make the hardware architecture more compatible with scalable manufacturing. It is a credible strategic proposition, not yet proof that scale, yield or unit economics will work in practice.

On 31 July 2026, after the Q2 balance-sheet date, IonQ completed its acquisition of SkyWater Technology. The official closing announcement says SkyWater will continue as a U.S.-based semiconductor-foundry subsidiary, offering advanced technology, wafer and packaging services. In theory, the combination could bring chip design, fabrication, packaging and quantum-system development closer together.

The upside is a tighter learning loop, a more secure supply chain and potentially better manufacturing control. The risk is equally clear: the company could become an expensive collection of loosely connected technologies. Vertical integration is only an advantage if it improves product performance, cycle times, yield, customer delivery and eventually manufacturing economics. A larger organisational chart is not the same thing as a moat.

Liquidity is not profitability

IonQ had substantial liquidity at 30 June 2026, reporting $1.24 billion of cash and cash equivalents, $883 million of short-term investments and $840 million of long-term investments in its 10-Q. That gives management time to invest, but it does not remove the need for operating discipline. The same filing reports a $1.06 billion net loss for the first six months of 2026, including significant non-cash and valuation items.

A long runway can support ambitious research and acquisitions. It can also make it easier to postpone hard capital-allocation choices. I would therefore monitor cash burn separately from accounting losses, while taking neither lightly. The central question is whether incremental gross profit and commercial cash generation begin to cover more of the operating base before dilution or additional financing becomes the default answer.

Where I could be wrong

  • Organic demand may be stronger than I expect. Repeat enterprise deployments and RPO conversion could demonstrate that quantum work is moving from experimentation into recurring operational spend faster than the financial statements currently show.
  • The integrated stack may be more valuable than the segments imply. Oxford Ionics, SkyWater and IonQ’s software and networking capabilities could reinforce each other through faster development, manufacturing control and a better customer offer.
  • I may understate strategic-customer value. Government, research and enterprise relationships can have longer purchasing cycles, but may create a base for follow-on programmes that is not visible in a single quarter.
  • I may overemphasise near-term margins. Some investment is unavoidable in a technically demanding market. The important distinction is between purposeful investment with measurable commercial returns and open-ended spending protected by a strong balance sheet.

The risks I would not minimise

  • Acquisition effects: reported growth can include acquired operations and integration timing, rather than representing organic demand for IonQ quantum-computing products.
  • RPO conversion: contracted demand is not recognised revenue or cash, and its timing, margin and collectability matter.
  • Architecture uncertainty: the eventual hardware and error-correction winner remains uncertain. IonQ competes with much larger, better-resourced companies as well as specialist quantum rivals.
  • Losses and cash burn: substantial liquidity is valuable, but the business remains materially loss-making and needs a credible route to improving economics.
  • Integration and capital allocation: rapid acquisitions can strain management, dilute focus and consume capital before synergies are demonstrated.
  • Dilution: warrants, equity-funded deals and employee awards can increase the share count and change the claim of existing shareholders.
  • Technical claims: company-reported benchmarks and roadmaps are useful inputs, not independent evidence of lasting commercial superiority.

My monitoring checklist

  • Separate organic growth from acquisition-led revenue in each filing and results release.
  • Look for repeat customer deployments, renewal evidence and a rising share of revenue from customers using more than one product.
  • Track RPO against subsequent revenue recognition, cash collection and disclosed delivery timing.
  • Follow gross margin, cost of revenue and operating cash burn, rather than focusing only on revenue growth.
  • Read integration updates for Oxford Ionics and SkyWater, including retention of key people, product milestones and any evidence of manufacturing yield or cost improvement.
  • Review whether foundry and packaging operations produce real manufacturing economics, not just strategic language.
  • Update the fully diluted share count for warrants, acquisition consideration and employee equity awards.

Bottom line

IonQ is becoming more commercial in the straightforward sense that it is reporting larger revenue, broader customer exposure and more contracted demand. The more demanding thesis is still ahead of it. It must show that those signals convert into recurring, cash-generative revenue, better gross margins and a coherent integrated platform.

That is why I would judge the business through revenue quality, not just the roadmap. The Portfolio provides the broader context for my holdings. This article records the questions I would revisit as IonQ reports new information.

Disclosure: This article is for information and personal research only. It is not investment advice, a recommendation, or an offer to buy or sell any security. Quantum-computing equities are high risk and can be volatile. Primary sources considered include IonQ’s Q2 2026 Form 10-Q, FY2025 Form 10-K and official Q2 results release.

BitMine (BMNR) Investment Thesis: ETH Per Fully Diluted Share

For a personal investor, BitMine is easy to misclassify. The legacy name points to mining, while the headline number most people repeat is the size of its ETH treasury. Neither is the unit of analysis I find most useful. The question is simpler, and harder: does each common share have a growing claim on ETH after allowing for every share, warrant and senior claim that can sit ahead of it?

That is why my starting metric for BitMine Immersion Technologies, Inc. (NYSE: BMNR) is ETH per fully diluted common share, not total ETH held. This is a research framework, not a recommendation to buy or sell BMNR.

What BitMine is today

BitMine describes itself in its quarterly report for the period ended 31 May 2026 as a blockchain-technology infrastructure company spanning institutional digital-asset staking and validation, bitcoin mining and strategic digital-asset management. Its stated operating focus has shifted towards institutional-grade staking and validation infrastructure, alongside an ETH treasury strategy. The older mining identity is therefore context, not the whole present-day investment case.

The same filing says the company acquired Pier Two in March 2026 through MAVAN Holdings, and launched MAVAN, the Made in America Validator Network, as a proprietary institutional-grade Ethereum staking platform. Pier Two provides non-custodial staking infrastructure, validator operations, staking-as-a-service and related technology services. BitMine says it holds 98% of MAVAN Holdings, with Ethereum Tower LLC holding the remaining 2%.

That makes BMNR a hybrid. It is an equity claim on a highly volatile ETH-linked balance sheet, financed through capital markets, with a developing validator-services operation attached. The valuation cannot be reduced to a conventional mining multiple, and it should not be reduced to a treasury headline either.

Why ETH per fully diluted share matters more than total ETH

A treasury can expand while the economic claim of a common shareholder falls. If the company issues common equity below the value of the ETH claim it acquires, or creates warrants and senior instruments on unattractive terms, the numerator can rise while the denominator rises faster. Total tokens are then a flattering but incomplete number.

My working calculation would start with ETH and ETH-equivalent economic exposure, then subtract or separately value obligations and senior claims where appropriate. It would divide that result by a conservative fully diluted common-share count. “Fully diluted” should mean more than shares currently outstanding: it needs to include in-the-money or potentially dilutive warrants, convertible or preferred structures where their terms justify inclusion, equity awards and known issuance capacity where it is economically relevant.

This is not a claim that every instrument has the same conversion outcome. It is a discipline against assuming that the basic share count is the whole capital structure. The 10-Q reported 603,226,394 common shares outstanding as of 9 July 2026, a date after the 31 May balance-sheet date. It also discloses a large ATM programme, common-stock issuance, outstanding warrants and later preferred-stock activity. Those facts make a single static per-share figure less useful than a regularly updated, fully diluted range.

A useful monitoring table would therefore show four moving lines: ETH held or economically attributable to common equity; basic common shares; a conservative fully diluted share count; and ETH per fully diluted share. If management raises capital, the key test is whether the last line improves, not whether the first one simply gets bigger.

The investment question is not whether BitMine can accumulate more ETH. It is whether the common shareholder’s proportional ETH claim increases after the financing needed to do it.

The financing stack is part of the asset

The capital structure is not an administrative footnote here. In the nine months ended 31 May 2026, BitMine reported $11.87 billion of gross proceeds from the sale of 340.75 million common shares through its ATM offering, within total equity-financing proceeds of $12.24 billion. The company also disclosed a September 2025 issue of common shares and warrants, with warrants exercisable for up to 10.44 million shares, subject to adjustment. An earlier 10-K says the ATM programme permitted sales of up to $24.5 billion of common stock from time to time.

Those disclosures do not determine whether any particular issuance was good or bad for common holders. They establish why the price and terms of issuance must be monitored. Issuing equity at a premium to conservative net asset value can be accretive to per-share ETH economics. Issuing at a discount, or layering in claims that absorb upside or sit senior to common, can have the opposite effect.

Preferred instruments deserve the same scrutiny. The 10-Q notes that no preferred shares were outstanding at 31 May 2026, but also records authorised preferred capacity and subsequent preferred-stock events. A common shareholder should read terms rather than rely on labels: dividend obligations, liquidation preference, convertibility, redemption rights and anti-dilution provisions all influence the residual claim.

How staking and MAVAN could change the analysis

A pure treasury wrapper has limited ways to create value beyond financing, custody and capital allocation. A functioning validator-services layer could add a different source of economics: staking rewards and fees for operating infrastructure. BitMine reported $45.7 million of staking and validation revenue in the three months ended 31 May 2026, and $56.9 million in the first nine months. The filing says native staking began in November 2025, while Pier Two contributed $3.5 million of staking revenue after its acquisition date.

That revenue should not be treated as a mature, recurring annuity. The filing explains that the company earns digital assets for validation services, recognises the full blockchain reward as revenue when acting as principal node operator, and records distributions to delegators or participants as cost of sales. Reported revenue, token prices, validator participation and operating costs can all move. The relevant question is whether MAVAN can develop independently valuable client relationships, service quality and margins, rather than merely stake BitMine’s own ETH.

The company’s official investor-relations hub is the practical place to follow presentations and new disclosures, but the filed financial statements remain the better anchor for the underlying operating record. For an evergreen thesis, I would look for sustained third-party activity, transparent economics, client retention and evidence that staking revenue covers the additional operational, security and compliance burden.

The risks are not peripheral

  • Per-share dilution and seniority: Total ETH can rise while the common-holder claim per share worsens. ATM capacity, share issuance, warrants and preferred instruments can materially change the residual claim.
  • ETH concentration and mark-to-market volatility: A concentrated crypto balance sheet can swing sharply with ETH. Changes in ETH price can affect treasury value, staking economics, liquidity and market perception at the same time.
  • Staking, custody and protocol risk: Validator downtime, slashing, custody failure, counterparty issues, regulatory change and Ethereum protocol changes can impair returns or create liabilities.
  • MAVAN execution risk: MAVAN launched in March 2026 and has limited commercial operating history. BitMine itself identifies competition from established providers, the challenge of winning and retaining institutional clients, and potential harm from service-level failures.
  • Controls and governance: The 10-Q discloses material weaknesses in internal control over financial reporting and says remediation must be monitored. A rapidly changing balance sheet needs unusually reliable controls and disclosure.
  • Capital allocation beyond ETH: The filing also describes strategic investments, including positions outside the core treasury and validator model. These can add optionality, but they can also obscure the per-share ETH thesis and increase capital-allocation risk.

Where I could be wrong

I could be too narrow in treating ETH per fully diluted share as the dominant number. MAVAN may become a valuable operating business whose client relationships, technology and cash generation warrant a separate valuation. Conversely, I could be too generous if treasury assets are less liquid, more encumbered or more exposed to senior claims than a simple token count suggests.

I could also underestimate the difficulty of separating capital-market timing from operating performance. A financing that looks dilutive in a snapshot may fund ETH purchases at a favourable point in the cycle. Equally, a higher ETH price can conceal weak per-share capital allocation. The point is not to pretend the answer is static. It is to keep the denominator as visible as the numerator.

My monitoring checklist

  • Recalculate ETH per fully diluted common share after each 10-Q, 10-K, prospectus supplement or material financing disclosure.
  • Track common shares, warrants, preferred terms, ATM usage and any repurchases alongside ETH acquisitions.
  • Separate filed balance-sheet figures from date-labelled company-reported treasury updates. Do not treat a press-release token total as the latest audited or reviewed balance sheet.
  • Watch MAVAN’s third-party client traction, revenue mix, costs, uptime and any disclosed slashing, custody or counterparty events.
  • Read management’s updates on the disclosed internal-control weaknesses and their remediation.
  • Assess non-core investments separately rather than assuming each is part of the ETH treasury claim.

Bottom line

BitMine is not best understood as a conventional miner, nor simply as a large ETH headline. It is a capital-allocation vehicle built around ETH exposure, increasingly paired with validator infrastructure. The durable question for a common shareholder is whether financing and operations make the claim per fully diluted share better over time.

That makes this a thesis that needs an active checklist, not blind conviction. I will keep the Portfolio context separate from this company analysis, and I will update my view only when filings and material disclosures change the per-share economics.

Disclosure: This article is for information and personal research only. It is not investment advice, a recommendation, or an offer to buy or sell any security or digital asset. Crypto-linked equities and digital assets are highly volatile and can result in substantial or total loss.

Primary sources considered: BitMine’s Form 10-Q for the period ended 31 May 2026, its Form 10-K for the year ended 31 August 2025, and its official investor-relations hub.
Portfolio Rebalancing UK: Rules for Drift, Risk and Deliberate Decisions

For education and information only. This page is not personal financial, investment, tax or legal advice, and is not a recommendation or invitation to buy, sell, transfer or hold an investment. Investing involves risk and you can lose money, including the amount invested.

Rebalancing is not a reason to trade for the sake of activity. It is a pre-set response to a portfolio moving away from the risks you intended to own.

Start with a written target

A target can be a percentage split, a maximum position size, a cash buffer or a rule about how much one theme may dominate. Without a target, “rebalancing” often becomes a story told after a price move.

Three sensible triggers to consider

  • Calendar: review at a defined interval, without assuming every review requires a trade.
  • Threshold: review when an allocation moves far enough from its range.
  • Cash-flow: use new contributions or withdrawals to reduce drift before selling assets.

UK considerations

Rebalancing inside an ISA or pension can have different tax consequences from activity outside a wrapper. Costs, spreads and tax can all matter. Check current rules with HMRC or an adviser where relevant. The FCA’s diversification guidance explains why avoiding over-reliance on one investment can help manage risk, but diversification does not prevent loss.

What this framework cannot decide

No article can set your target allocation, risk tolerance or rebalancing frequency. A concentrated investor may deliberately operate with different rules from an index investor. The key is knowing the trade-off and writing the rule before the portfolio tests it.

What rebalancing cannot do

Rebalancing can change risk exposure but does not prevent losses or guarantee returns. It may create costs and tax outside tax wrappers. It cannot determine whether a target allocation suits you, whether an asset will recover or whether a transaction is appropriate for your circumstances. Use it as a documented process, not a substitute for judgement.

Related reading

How to Research a Stock Before You Buy: A Filing-First Checklist

For education and information only. This page is not personal financial, investment, tax or legal advice, and is not a recommendation or invitation to buy, sell, transfer or hold an investment. Investing involves risk and you can lose money, including the amount invested.

Research cannot remove uncertainty. It can make the uncertainty visible before capital is committed. A good outcome is sometimes “I do not understand this well enough yet.”

1. Start with the business, not the chart

Describe what the company sells, who pays, why customers stay and what could make that relationship less durable. If the business cannot be explained plainly, the ticker is not ready for a valuation discussion.

2. Read primary disclosures

Start with the investor-relations site and relevant filings. The SEC explains how 10-K and 10-Q reports describe a company’s business, risks and financial results. Read the business description, risk factors, MD&A, liquidity section and financial-statement notes.

3. Test the numbers against the story

  • Revenue quality: recurring or one-off, concentrated or diversified.
  • Margins and cash conversion: does cash support reported profits?
  • Balance sheet: debt maturities, covenants, liquidity and financing needs.
  • Share count: dilution from compensation, warrants, convertibles or future capital raises.
  • Valuation: what assumptions are embedded in the price, and what could make them wrong?

4. Write the bear case

Name the strongest alternative explanation. Then write the evidence that would invalidate the view and the next filing or milestone that can test it. Do not use a falling price as the only decision rule.

5. Decide, defer or pass

A position size is a risk decision, not a confidence score. Correlation with existing holdings, liquidity needs and the ability to withstand a loss matter as much as the apparent upside.

Related reading

Investment Thesis Template: A Research Checklist for Long-Term Investors

For education and information only. This page is not personal financial, investment, tax or legal advice, and is not a recommendation or invitation to buy, sell, transfer or hold an investment. Investing involves risk and you can lose money, including the amount invested.

A written thesis is not a prediction. It is a decision record: what you believe, why you believe it, what evidence supports it and what would change your mind.

The one-page template

  • Business in one sentence: what the company sells, who pays and why the relationship may endure.
  • What must be true: name the two or three assumptions that drive the outcome.
  • Evidence: link the filing, investor presentation or other primary source, date it and record the next check.
  • Financial quality: revenue, margins, cash conversion, debt, liquidity and customer concentration over more than one period.
  • Valuation: show assumptions and a range. A valuation is an interpretation, not a fact.
  • Risks and invalidation: write the strongest bear case and the evidence that would break the view.
  • Dilution: check basic and diluted shares, options, warrants, convertibles and financing capacity.
  • Position decision: set an initial size, a maximum and conditions for adding, trimming or doing nothing.

Use primary sources first

For US companies, the SEC’s 10-K and 10-Q guidance is a useful starting point. Read the business description, risk factors, liquidity discussion, financial statements and notes before adopting a narrative from elsewhere.

The rule that matters most

Write the invalidation test before any action. A share-price fall alone is not proof that a thesis is broken. A failed milestone, deterioration in customer retention, an unexpected capital raise or a weakening competitive position may be more informative. The point is to prevent a later outcome from rewriting the original reason for owning something.

Related reading

Rome Resources (AIM: RMR): Why Resource Definition Matters More Than Headline Potential

Rome Resources is a high-risk exploration thesis, not a recommendation. I am assessing it as a personal investor by asking a narrower question than “could this become a big tin story?”: can the Kalayi discovery move from an early geological promise to an asset with a defined, financeable development path?

The distinction matters. A small explorer can produce exciting drill results and still fail to create durable value if resource confidence, tenure, metallurgy, funding or on-the-ground execution do not follow. For RMR, the headline potential is interesting. The investable work is in the proof still required.

The project and what is verified today

Rome Resources describes Kalayi as part of its Bisie North tin project in North Kivu, Democratic Republic of Congo. The company’s official project page places it near the Bisie Ridge, but proximity to established mines or other prospects is not evidence that Kalayi itself is economic. Each deposit has to earn that conclusion through its own drilling, engineering, recovery work, permitting and financing.

The key recent factual step is the company’s 2 September 2026 updated mineral resource announcement, which reported a 45% increase in contained tin. Management has also highlighted improved grade. That is the right direction, but the Kalayi estimate remains an Inferred Mineral Resource, not a reserve. It is therefore an early confidence category, not a mine plan and not proof of future extraction or profitability.

Why resource definition and grade matter

Contained-metal growth can attract attention, yet the more important question is what sits underneath the headline. Better definition can clarify continuity, geometry, thickness and the distribution of higher-grade zones. Higher grade can help a future project, because it may improve the amount of payable metal recovered per tonne processed. Neither outcome should be assumed from a resource headline alone.

For a remote tin project, the eventual economics will depend on far more than grade: mineable shapes, dilution, recovery, processing design, concentrate quality, transport, sales terms, capital intensity and operating costs all matter. I would rather see RMR turn uncertainty into successive technical evidence than rely on comparisons with nearby operations.

The milestones that would strengthen the case

  • Resource confidence: drilling that improves the density and continuity of the Kalayi data set, with a transparent explanation of how the resource model changes.
  • Grade and metallurgy: repeatable results that show whether mineralisation can be recovered into a saleable concentrate, rather than isolated high-grade observations.
  • Licence conversion: evidence that the current programme supports conversion of PEPM 13274 into a full mining licence. The company’s 15 June 2026 announcement makes clear that conversion remains a programme and process, not a completed outcome.
  • Ownership consolidation: progress on the proposed increase in Kalayi ownership only once its conditions are actually satisfied. An expected ownership rise is not the same as an owned interest today.
  • Capital discipline: a funding plan that matches the scale and duration of exploration, technical studies, permitting and site execution without making the share count an afterthought.

What would weaken it

  • Drilling that expands tonnage without improving confidence, continuity or practical mineability.
  • Metallurgical or concentrate results that make recovery, marketing or transport harder than the geological story suggests.
  • Delays or conditions around licence conversion, ownership consolidation or local operating permissions.
  • Financing that repeatedly extends the runway while creating substantial dilution or leaving a material warrant overhang.
  • A deterioration in security, logistics or jurisdictional conditions in North Kivu.

Where I could be wrong

The optimistic case could be wrong because an Inferred resource may not convert into a mineable, higher-confidence inventory on attractive terms. It could also be wrong because licence conversion and any ownership increase are conditional, rather than completed facts. North Kivu brings material security, logistics and jurisdiction exposure that cannot be diversified away at project level.

Funding is another central risk. Exploration cash is limited relative to the work that would be needed to de-risk, study and develop a remote project. The company’s half-year results and September 2026 financing announcement should be read with that in mind. Future capital will be needed, and dilution plus a warrant overhang can be very material for shareholders.

Finally, the usual development risks are not background noise here. Remote execution, metallurgy, concentrate marketing and the tin price can each change the value of the same geological asset. A stronger resource estimate would be helpful, but it would not neutralise those risks.

My monitoring checklist

  • Does each drilling update add confidence and continuity, not just a larger headline?
  • Are grade, width, recovery and concentrate specifications moving toward a coherent processing case?
  • Has the mining-licence conversion moved from programme to verified outcome?
  • Have the conditions for the proposed ownership increase been met, and on what terms?
  • How much cash is available, what warrants remain outstanding, and what work is funded before the next raise?
  • Are security, logistics and operating conditions in North Kivu improving, stable or worsening?
  • Does the tin market support a plausible development case without requiring an exceptional price environment?

Bottom line

RMR is interesting to me because Kalayi’s resource growth and improved grade create a more substantial technical question than the earlier discovery-stage story. The thesis is not that a resource update makes the project economic. It is that disciplined resource definition, credible permitting progress, ownership clarity and adequately funded execution could make the answer clearer over time.

Until then, this belongs in the speculative end of a portfolio process. Readers can see how I frame individual holdings and risk at the Portfolio page.

Disclaimer

This article records a personal research view, not investment advice or a recommendation to buy, sell or hold any security. Small-cap exploration companies can be highly volatile and investors can lose all of their capital. Verify primary disclosures, consider your own circumstances and seek regulated advice where appropriate.

Surf Air Mobility (SRFM) Investment Thesis: Can Aviation Software Become the Real Business?

Personal investor framing: I am not treating Surf Air Mobility as an imminent electric-aircraft story. The question I find more investable, and still highly speculative, is whether a real operating airline can become the proving ground for aviation software that other operators will pay to use. Everything else has to be judged against the company’s financing and execution risks.

What the business is today

Surf Air Mobility operates scheduled regional airline services and on-demand private charter, while developing SurfOS software and pursuing aircraft electrification. It is not a software company with established recurring revenue, and it is not a certified electric regional-aircraft operator.

For the quarter ended 30 June 2026, the company reported $29.5 million of revenue, up 8% year on year. Scheduled-service revenue was $17.4 million, down 19%, while Surf On Demand private-charter revenue was $12.1 million, up 101%. The 10 August 2026 results release reported a $28.1 million net loss and a $10.5 million adjusted EBITDA loss. Those figures show both the operational base and the distance still to travel.

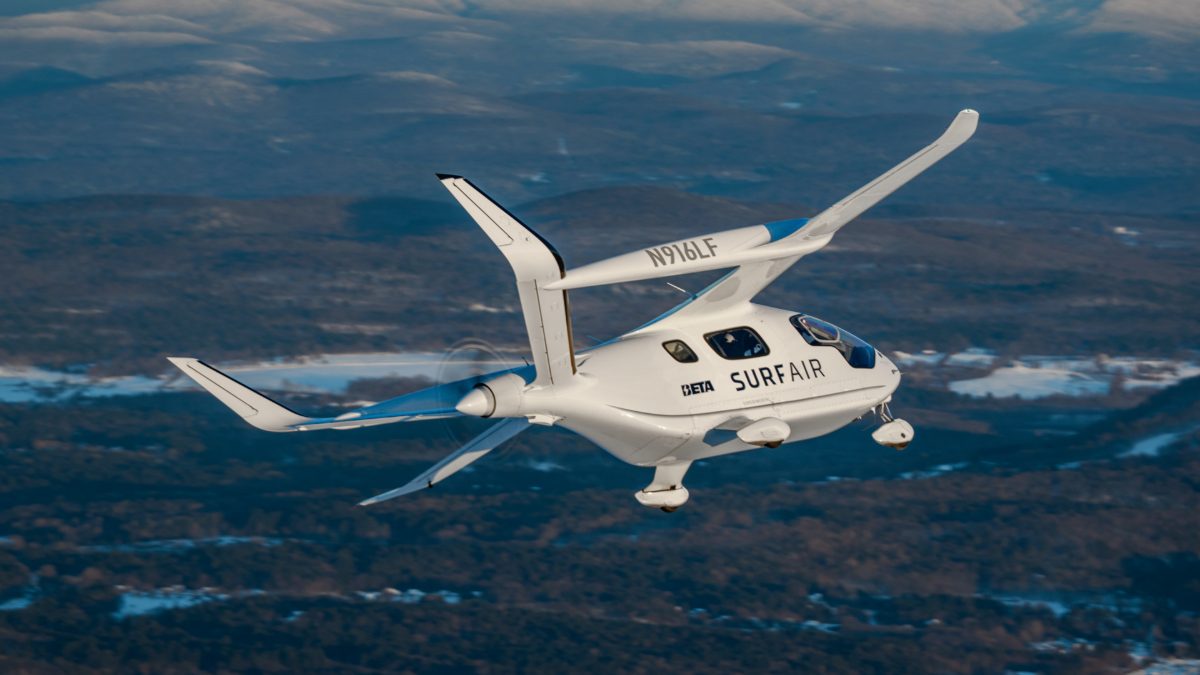
BETA ALIA electric aircraft featured on Surf Air Mobility website, source: Surf Air Mobility
Official Surf Air Mobility website image of a BETA ALIA aircraft. Source: Surf Air Mobility.

Why SurfOS could matter

A software layer that improves dispatch, recordkeeping, brokerage or utilisation could have better incremental economics than owning and operating aircraft. Internal airline operations generate flights, dispatch decisions, maintenance records and workflow problems in the real world. If the product works for independent operators, that operational evidence becomes more valuable.

Two dated signals are worth separating from promotional language. On 25 June 2026, Surf Air announced Wheels Up as launch customer for Enterprise BrokerOS. That is external-customer validation, not proof of scaled recurring revenue. On 26 August 2026, Surf Air announced that the FAA had named OperatorOS an authorised system for electronic signatures and recordkeeping for the company’s airlines. That is a practical workflow milestone, not blanket FAA approval of every software use case or a guarantee of commercial adoption.

The actual investment case

My base case is not that electrified regional aviation arrives quickly enough to rescue the economics. It is that airline operations become less capital-intensive and more resilient, while SurfOS earns a right to be evaluated as a separate aviation-software opportunity. If external customers pay, renew and expand, the market may eventually be able to value more than an airline with a difficult balance sheet.

That needs operational improvement, third-party software adoption and adequate funding without repeated unacceptable dilution. The 10-Q for the quarter ended 30 June 2026 reported a $48.4 million net loss for the first six months of 2026 and $13.4 million of cash used in operating activities. Electrification is valuable optionality, not the valuation premise. Certification, aircraft availability, powertrain performance, maintenance capability and partner execution remain dependencies.

Evidence readers should track

  • External software revenue: contract value, deployment scope, renewal, expansion and separately disclosed revenue.
  • OperatorOS usage: evidence that electronic workflows improve reliability, turnaround, compliance effort or cost.
  • Airline economics: scheduled service, charter mix, revenue per flight, cancellations, fuel exposure and cash generation.
  • Capital structure: share issuance, convertibles, warrants, covenants and liquidity requirements.
  • Electrification milestones: distinguish agreements and demonstrations from certified aircraft and commercial routes.

Where I could be wrong

  • Cash flow and financing: the 30 June 2026 10-Q said the company had losses from operations, negative operating cash flows and a working-capital deficit.
  • Debt, tax and defaults: the same filing disclosed defaults on certain excise and property taxes and certain debt obligations, including about $11.1 million of federal excise-tax liability and about $0.9 million of property-tax liability at 30 June 2026.
  • Very material dilution: the 10-Q discloses an April 2026 registered direct offering of 13,318,181 shares at $1.10 per share, alongside other equity-linked financing and reserve requirements. Business improvement may not become a per-share win.
  • Uncertain airline economics: route rationalisation and charter growth do not prove durable profitability.
  • Software may stay early: FAA authorisation and a launch customer are credible signals, but not scaled recurring revenue or a broad moat.
  • Electric aviation dependency: certification and commercial deployment depend on powertrain and aircraft partners, regulators, capital and infrastructure.

A monitoring checklist

  1. Read each quarterly filing for operating cash flow, liquidity, debt terms, tax/default disclosures and new securities.
  2. Compare software announcements with disclosed revenue, customer count, renewals and implementation progress.
  3. Test whether airline improvement survives a full seasonal cycle.
  4. Separate adjusted EBITDA guidance from GAAP losses and cash generation.
  5. Demand dated, regulator-backed evidence before assigning value to electric-aircraft milestones.
  6. Reassess whenever financing changes the share count or seniority of claims.

My current conclusion

Surf Air Mobility is interesting because it has an aviation operating environment in which software can be tested. The credible thesis is a long, risky attempt to turn airline operating data and workflows into a software product that third parties value. The balance-sheet risk, dilution risk and lack of scaled software revenue mean the burden of proof remains high.

For the wider context of how I think about individual holdings and concentration, see my portfolio.

Sources

Disclosure: This is a personal research note, not financial advice or a recommendation to buy or sell any security. I can be wrong. Verify primary sources and consider your own circumstances before making an investment decision.

Concentrated Investing: Position Size, Risk and Review Rules

Concentrated Investing: Position Size, Risk and Review Rules

Short answer: concentration can make an investor’s best ideas matter more, but it also makes analytical, behavioural and financial mistakes more expensive. This is a personal process for thinking about that trade-off, not a model allocation to copy.

For education and information only. This is not personal financial, investment, tax or legal advice, and it is not a recommendation to buy, sell or hold any investment. A concentrated portfolio can lose substantial value.

Why concentration is deliberate, and why it is hazardous

A concentrated portfolio is not automatically more thoughtful than a diversified one. It is simply more exposed to the accuracy of a smaller number of decisions. A business can disappoint, a valuation can compress, a financing can dilute existing holders or several seemingly separate holdings can fail for the same macro reason.

The FCA explains in its diversification guidance that spreading investments can reduce reliance on any one investment performing well. That does not mean diversification eliminates losses, or that a concentrated investor should pretend the risk is not there. It means the trade-off should be visible before capital is committed.

Start with risk capacity, not conviction

  • What cash is needed for emergencies, near-term commitments or debt?
  • How would a severe drawdown affect work, sleep and the ability to make good decisions?
  • Which holdings share a sector, customer, funding or macroeconomic exposure?
  • How liquid is the position if the thesis changes?
  • What would force a sale at the worst possible moment?

There is no universally correct maximum position size. A number that is tolerable for one investor can be reckless for another. The important work is defining a personal initial size, maximum size and conditions for changing either.

My position-sizing framework

  1. Start with the downside. Evidence that is early, weak liquidity, high leverage, external financing needs or correlated exposure all argue for a smaller initial position.
  2. Write the maximum before the outcome. Do not let a rising share price quietly turn a position into a portfolio decision you never chose.
  3. Separate adding from averaging down. A lower price is not evidence that a thesis is stronger. Re-check the original assumptions first.
  4. Keep a do-nothing option. New information does not always require an immediate trade.

Track dilution and capital allocation

For businesses that use shares, options, warrants, convertibles or at-the-market facilities, ownership can change even while the headline business story sounds positive. Track basic and diluted share counts, outstanding awards, future financing needs and whether new capital has a credible route to creating per-share value.

Thesis review and invalidation

Every meaningful position needs a written original thesis, a bear case, observable milestones and specific invalidation conditions. A falling price is not automatically an invalidation event. Deteriorating unit economics, a broken customer relationship, an unexpected financing or a failed operational milestone may matter much more.

Keep a change log. It separates what was known at the time of the decision from the story hindsight wants to tell later.

What I will not claim

Concentration is not safety. Public disclosure of a holding is not an invitation to copy it. Past results do not make the process right. The point of a framework is not to make risk disappear. It is to make the decision, risk and reassessment criteria explicit.

Related reading